E-Invoicing in Professional Services: A Practical Guide for UAE Firms
The shift toward e-invoicing in professional services is becoming an important part of the UAE’s broader digital tax and finance transformation. For law firms, consulting companies, accounting practices, engineering firms, architecture businesses, and other professional service providers, the transition is not simply about replacing PDF invoices with electronic documents. It requires stronger data structures, process controls, system integration, validation, reporting, and reconciliation.
What Does UAE e-Invoicing Mean for Professional Services?
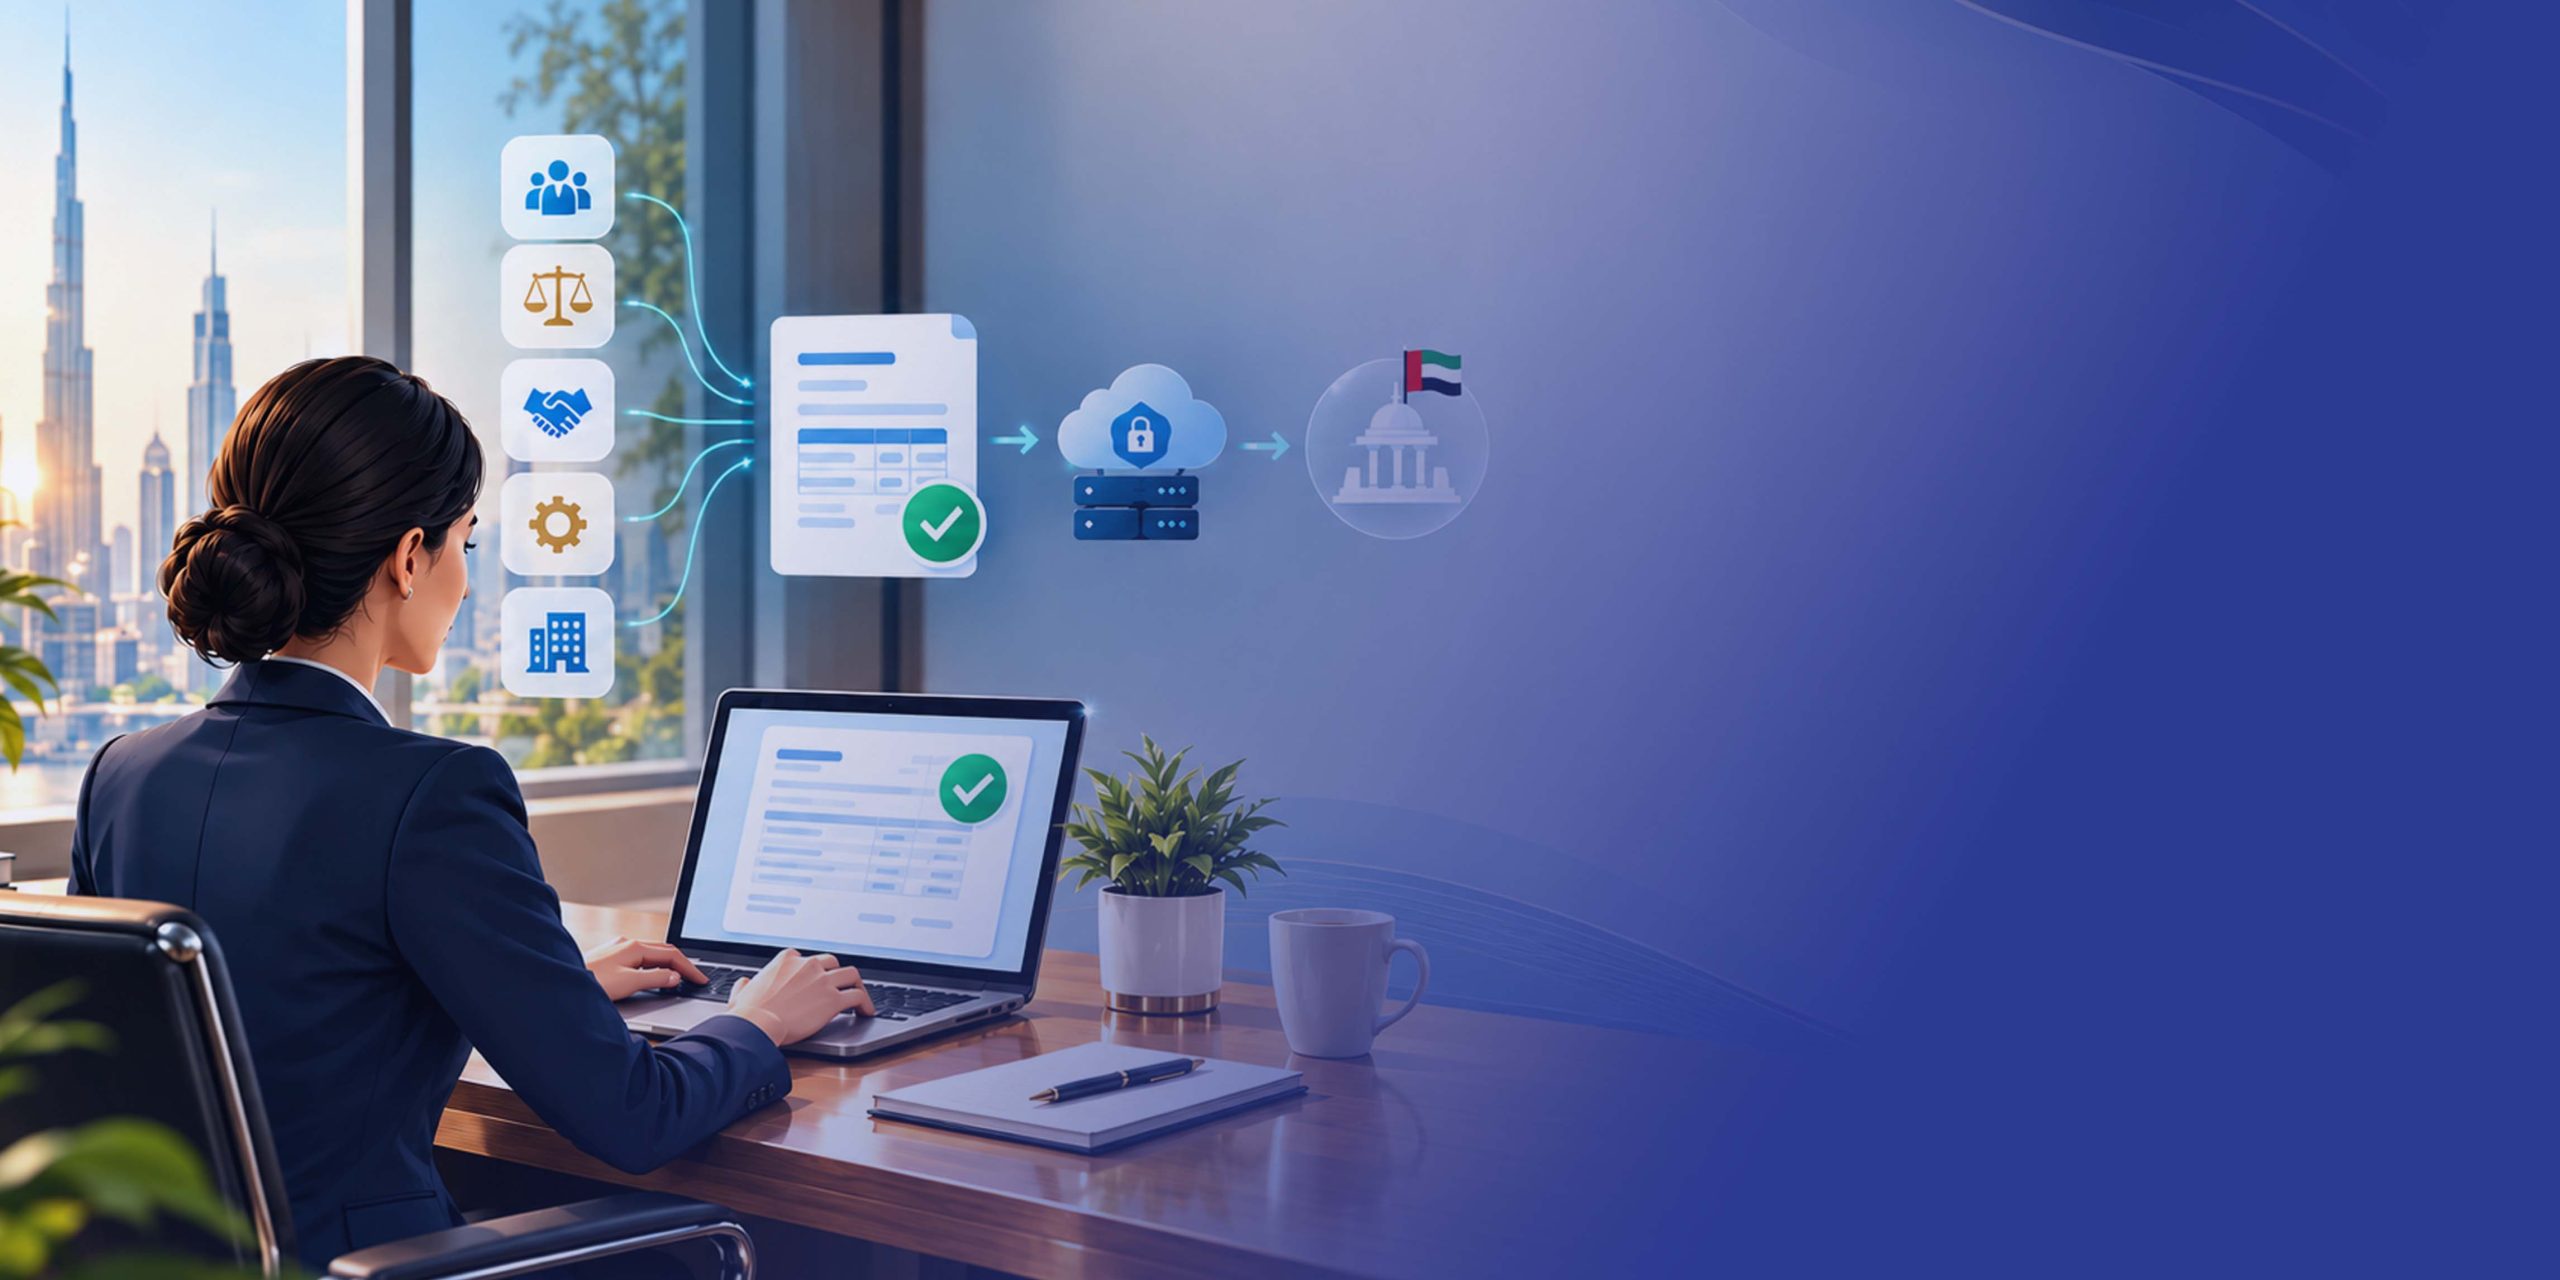
The UAE Ministry of Finance defines an eInvoice as structured invoice data that is issued and exchanged electronically and reported to the Federal Tax Authority. PDFs, Word documents, scanned invoices, images, and invoices sent by email are not considered eInvoices. The UAE model uses Accredited Service Providers and a decentralized continuous transaction control and exchange approach.
For businesses, e-invoicing in professional services therefore means moving from document-based billing toward a connected digital process in which invoice data can be validated, exchanged, and reported electronically.
The scope is particularly relevant to professional services because these businesses often manage recurring retainers, project-based billing, milestone invoices, expenses, credit notes, multiple tax treatments, and cross-border clients.
Why Professional Services Need to Prepare Early
Professional service firms often have billing processes that look simple on the surface but involve significant data complexity. A single client engagement can include multiple consultants, departments, projects, cost centres, billing rates, reimbursable expenses, discounts, VAT treatments, and contractual milestones.
A successful e-invoicing in professional services strategy should therefore begin with process mapping rather than software selection alone.
Businesses should identify:
- How invoices are created today
- Which systems hold customer and tax data
- How project and billing information reaches finance
- How VAT information is validated
- How credit notes are generated
- How invoices are approved
- How rejected invoices are handled
- How payment and receivable status is reconciled
- Which customers require B2B or B2G invoicing
This assessment helps firms identify gaps before they become operational problems.
Key Challenges for Professional Service Firms
- Complex Billing Models
Professional service firms may bill by hour, milestone, fixed fee, retainer, subscription, or a combination of models. An e-invoicing workflow needs to capture the relevant information accurately and consistently.
- Data Quality
Customer names, tax registration information, addresses, tax categories, invoice references, service descriptions, and amounts must be reliable. Poor master data can lead to validation failures and downstream reconciliation issues.
- Multiple Systems
Many firms use CRM platforms, practice-management systems, project-management tools, accounting software, ERP platforms, and payment systems. Connecting these systems is a core part of e-invoicing in professional services.
- Credit Notes and Adjustments
Professional services frequently involve scope changes, cancelled work, billing corrections, discounts, or revised project values. Finance teams need clear workflows for issuing and tracking electronic credit notes and related adjustments.
- Reconciliation
Sending a compliant invoice is only one part of the process. Finance teams also need visibility into whether an invoice was accepted, rejected, delivered, reported, and ultimately matched against accounting and payment records.
What Should a UAE Professional Services Firm Look for in an e-Invoicing Platform?
Choosing a UAE e-invoicing solution should go beyond checking whether the provider can transmit invoices.
A strong platform should support:
- ERP and accounting-system integration
- Structured invoice generation
- PINT AE and required UAE formats
- Automated validation before transmission
- Customer and supplier master-data checks
- Credit note processing
- Invoice status tracking
- Exception and rejection management
- Reconciliation workflows
- Audit trails
- Secure data exchange
- Reporting and monitoring
- Scalable API connectivity
The objective should be to create an end-to-end finance workflow rather than another standalone invoicing tool.
The Role of Integration
For professional services, integration can determine whether e-invoicing becomes a productivity improvement or an additional administrative burden.
A firm may generate invoices from an ERP, calculate project fees in a professional-services platform, maintain customer information in a CRM, and reconcile payments through its accounting system. If these systems operate in silos, finance teams may still depend on spreadsheets and manual checks.
With well-designed integration, invoice information can move from the source system through validation and transmission while status information flows back into finance workflows.
This makes e-invoicing in professional services more useful as a finance transformation initiative rather than simply a compliance exercise.
Reconciliation: The Often-Overlooked Requirement
One of the biggest opportunities is connecting invoicing with reconciliation.
Consider a consulting firm that sends thousands of invoices across different clients and projects. If invoice status, receivables, tax information, and payment records are stored separately, finance teams may spend significant time investigating discrepancies.
An effective reconciliation process can help identify:
- Invoice-to-accounting mismatches
- Duplicate invoices
- Missing invoices
- Incorrect tax treatment
- Unmatched credit notes
- Payment allocation issues
- Rejected or failed invoices
- Differences between billing and receivables
This is where e-invoicing in professional services can contribute to better financial visibility, faster exception handling, and stronger internal controls.
UAE e-Invoicing Timeline and Readiness
The UAE has introduced a phased implementation approach. The Ministry of Finance has stated that businesses with annual revenue above AED 50 million must implement the system from 1 January 2027, while the ASP appointment deadline for affected businesses was extended to 30 October 2026. Businesses below AED 50 million have a later implementation phase beginning 1 July 2027, with ASP appointment by 31 March 2027.
Professional service firms should not wait until the mandatory date to begin testing. Early preparation gives finance and IT teams time to assess master data, map processes, test integrations, handle rejection scenarios, train users, and establish governance.
A Practical Readiness Checklist
Before going live, firms should review:
- Business scope – Identify applicable B2B and B2G transactions.
- Billing processes – Document every invoice and credit-note workflow.
- Master data – Clean customer, supplier, tax, and service information.
- Systems – Identify ERP, accounting, CRM, PSA, and billing integrations.
- Data mapping – Map existing fields to required e-invoice data elements.
- Validation – Test tax, totals, mandatory fields, and business rules.
- Rejection handling – Define ownership and escalation procedures.
- Reconciliation – Connect invoice status with accounting and receivable processes.
- Security – Review access controls, audit trails, and data protection.
- Testing – Run realistic scenarios before production.
- Governance – Assign responsibility across finance, tax, IT, and operations.
A structured approach to e-invoicing in professional services can reduce last-minute disruption and create a more controlled transition.
Beyond Compliance: The Strategic Opportunity
The most forward-looking firms will view e-invoicing as more than a regulatory requirement.
Once invoice data becomes structured and digitally connected, professional service organizations can potentially improve billing visibility, identify exceptions earlier, reduce manual intervention, strengthen audit readiness, and gain better insight into receivables.
For CFOs, the conversation should therefore move from “How do we send an e-invoice?” to “How do we use structured transaction data to improve the finance process?”
That shift in mindset can make e-invoicing in professional services a catalyst for broader finance automation.
Conclusion
UAE professional service firms should approach e-invoicing as a combination of compliance, technology, data governance, and finance transformation. The right preparation involves understanding billing complexity, improving master data, integrating core systems, testing real-world scenarios, and building reliable reconciliation and exception-management processes.
The firms that prepare early will be better positioned to meet regulatory requirements while also creating a more efficient and transparent finance operation. Ultimately, e-invoicing in professional services is not just about changing the format of an invoice; it is about creating a connected transaction process that can support the next stage of digital finance in the UAE.